The impact assessment in the CSRD (Corporate Sustainability Reporting Directive) is a central part of how companies disclose their effect on the world around them. The directive requires in-scope companies to report on their environmental, social and governance (ESG) impacts, and the carbon footprint is one of the most important data points in that assessment.
This article explains what the CSRD impact assessment involves, how it connects to the carbon footprint, and how the scope of the rules changed following the EU's 2026 simplification package.
What is the CSRD?
The CSRD is an EU directive that improves the transparency and comparability of the sustainability information companies disclose. It replaced the earlier Non-Financial Reporting Directive (NFRD), which is now repealed, and is built around reporting standards known as the European Sustainability Reporting Standards (ESRS).
What are the objectives of the CSRD?
- Provide comparable and reliable sustainability information to investors and other stakeholders.
- Integrate sustainability into corporate strategy and governance.
- Support sustainable investment and the transition to a more sustainable economy.
Which companies are affected? (2026 update)
The scope of the CSRD was significantly narrowed by the Omnibus I simplification. Directive (EU) 2026/470, published in the Official Journal on 26 February 2026 and in force since 18 March 2026, raised the thresholds so that the directive now applies mainly to large EU companies that exceed both more than 1,000 employees and more than 450 million euros in net turnover. It no longer reaches companies at the old 250-employee threshold. An earlier "stop the clock" directive (Directive (EU) 2025/794) had already postponed reporting deadlines for some companies.
For non-EU groups, the CSRD applies where they generate more than 450 million euros of net turnover in the EU and have an EU subsidiary or branch above 200 million euros. Member States must transpose the new rules in March 2027, and the first reports under the revised scope cover financial years starting on or after 1 January 2027, published in 2028. Non-EU parent companies start with financial years from 2028.
One point that is often reported the wrong way round: first-wave companies that now fall below the new thresholds still have to report financial years 2025 and 2026 unless their Member State explicitly exempts them. The exemption is not automatic.
Double materiality and the carbon footprint
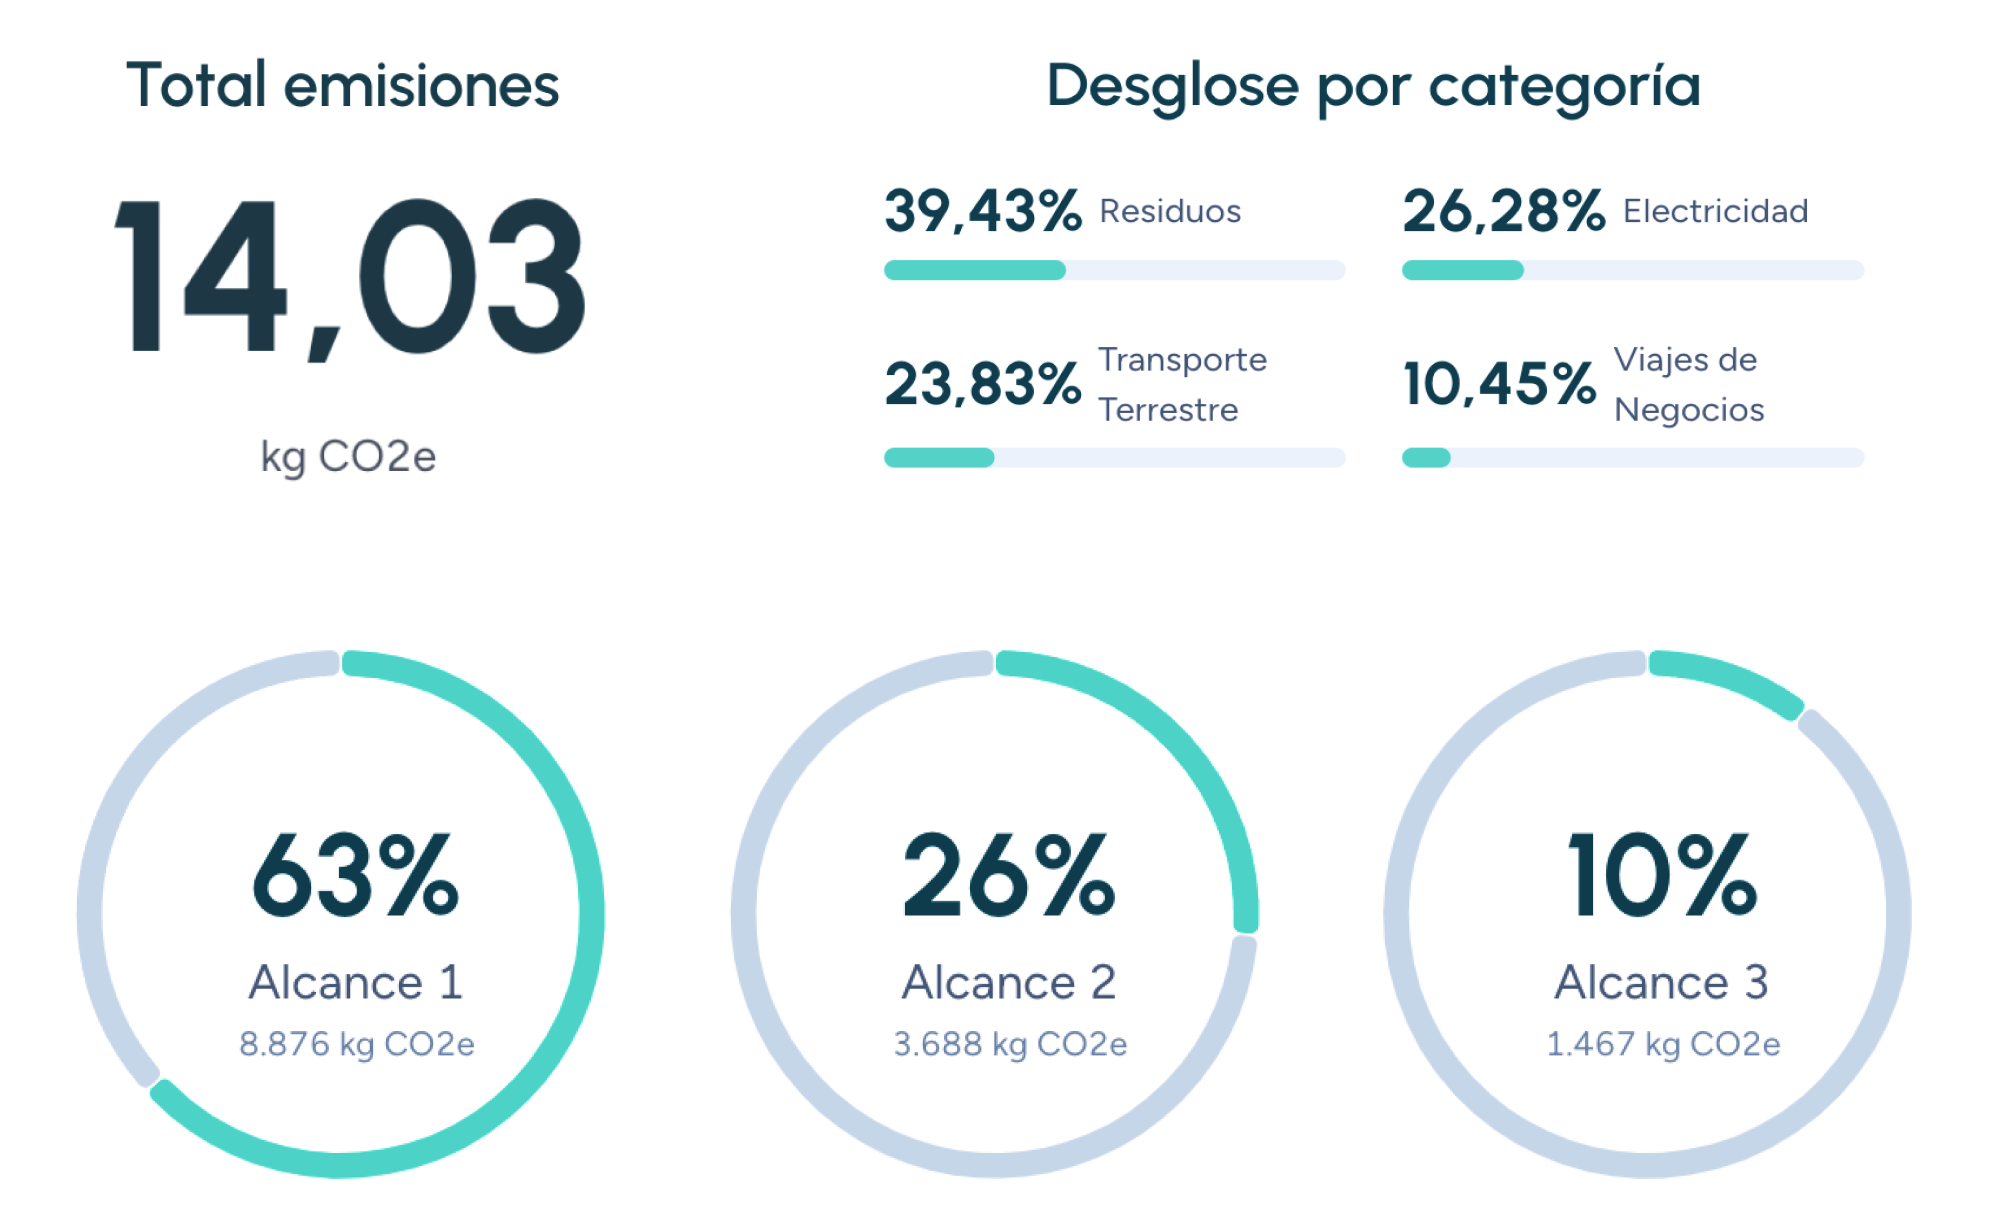
A defining feature of the CSRD is double materiality: companies assess both how sustainability matters affect the business (financial materiality) and how the business affects people and the environment (impact materiality). The carbon footprint is central to this, and the directive requires reporting of greenhouse gas emissions across Scope 1, Scope 2 and Scope 3.
- Scope 1: direct emissions from sources the company owns or controls (for example boilers and vehicles).
- Scope 2: indirect emissions from purchased electricity, heat or steam.
- Scope 3: other indirect emissions across the value chain, such as purchased goods, business travel and the use of sold products.
The revised ESRS were adopted by the European Commission in a delegated act on 3 July 2026. They cut more than 60% of the mandatory datapoints and more than 70% of all datapoints, remove voluntary disclosures and make the materiality assessment more flexible through a top-down approach. They apply to financial years starting on or after 1 January 2027, with early adoption possible for 2026. A separate delegated act adopted the same day set out the voluntary standard based on the VSME, which acts as a cap on the information companies can be asked to provide as part of someone else's value chain.
Benefits of the CSRD impact assessment
- Regulatory compliance: meeting EU requirements and avoiding penalties.
- Reputation: demonstrating a credible commitment to sustainability.
- Access to finance: easier access to sustainable finance and responsible investors.
- Risk and opportunity: identifying climate-related risks and opportunities, from rising carbon costs to demand for sustainable products.
- Innovation and efficiency: driving more sustainable products and processes, often with cost savings.
How to approach the CSRD impact assessment
- Understand the requirements: get familiar with the directive, the ESRS and the reporting obligations that apply to your company.
- Run the double materiality assessment: identify which impacts, risks and opportunities are material.
- Collect data: gather complete data on Scope 1, 2 and 3 emissions, which usually means engaging suppliers and value-chain partners.
- Calculate the carbon footprint: use recognised methodologies such as the GHG Protocol.
- Set targets and action plans: define reduction targets and concrete plans to meet them.
- Integrate and report: embed sustainability into strategy and disclose progress, subject to the limited assurance the directive requires. Directive (EU) 2026/470 removed the planned move to reasonable assurance, so limited assurance is the level that applies.
At Manglai we help companies measure their carbon footprint and prepare their CSRD sustainability reporting. Discover how Manglai can help you.
Companies that trust us
Related terms
See all termsCarbon sinks
Carbon sinks are natural or artificial systems that absorb and store more carbon dioxide than they emit, such as forests, oceans and soils, helping to offset emissions and slow climate change.
Carbon footprint registry
A carbon footprint registry documents and stores an organization's GHG emissions. In Spain, the official MITECO registry also recognises emission reductions and absorption projects.
Carbon intensity (CI)
Carbon intensity is a relative indicator that expresses greenhouse gas emissions per unit of activity, such as grams of CO2 per kWh or tonnes of CO2 per million euros of revenue.
Guiding businesses towards net-zero emissions through AI-driven solutions.
Product & Pricing
What is Manglai
Features
SQAS
GLEC
GHG Protocol
ISO-14046
ISO-14064
Miteco certification
CSRD
CSDDD
Digital Product Passport
EINF
Prices
Customers
Partners
Solutions by role
Environmental consulting
ESG management solutions
Financial directors
General directors
HR managers
Operations directors
Quality and environment directors
Senior management
Solutions for investment funds
Supply chain managers
Sustainability managers
Transport responsible
© 2026 Manglai. All rights reserved