A sustainability report is a document that companies use to communicate their commitment to sustainable development and to disclose their environmental, social and economic impact. It is a key instrument for transparency and accountability towards stakeholders, from investors and partners to employees, customers and society at large.
What is a sustainability report?
A sustainability report compiles and presents data on a company's environmental, social and economic performance. Its aim is to give a comprehensive view of the organisation's sustainability actions, usually aligned with international standards such as the Global Reporting Initiative (GRI) and, in the European Union, with the European Sustainability Reporting Standards (ESRS).
Reporting has become common practice for companies committed to the United Nations Sustainable Development Goals (SDGs). On the environmental side, a report typically covers carbon footprint measurement, decarbonisation strategies and, where relevant, offset projects.
Why a sustainability report matters
Producing a report is more than a legal obligation or a marketing exercise: it is a core tool for responsible management.
1. Transparency and trust
As stakeholders demand more transparency, a well-prepared report strengthens trust by showing concrete actions to reduce environmental impact and contribute to social well-being. Done credibly, it also helps a company avoid greenwashing.
2. Measuring and improving performance
Reporting forces companies to collect and analyse data on their performance, which helps identify areas for improvement, set clear targets and track progress over time.
3. Regulatory compliance
Sustainability rules are evolving quickly. In the European Union, the Corporate Sustainability Reporting Directive (CSRD) is the central reporting regime, replacing the repealed Non-Financial Reporting Directive and requiring disclosure through the ESRS.
The Omnibus simplification package, adopted as Directive (EU) 2026/470, raised the thresholds sharply: only EU companies with more than 1,000 employees and more than 450 million euros in net turnover now fall in scope, and the first reports cover financial years starting on or after 1 January 2027. The revised ESRS were adopted on 3 July 2026 and cut more than 60% of the mandatory datapoints. Assurance stays at limited assurance: the directive removed the planned move to reasonable assurance.
In Spain, Law 11/2018 on non-financial information and diversity (which transposed the previous directive and applies to companies with more than 250 employees meeting its criteria) remains in force pending the transposition of the revised CSRD into national law, expected in 2027.
Key components of a sustainability report
An effective report usually includes:
1. Company information
An overview of the organisation: mission, vision and values, corporate structure, main products and services, and geographic footprint.
2. Environmental impact
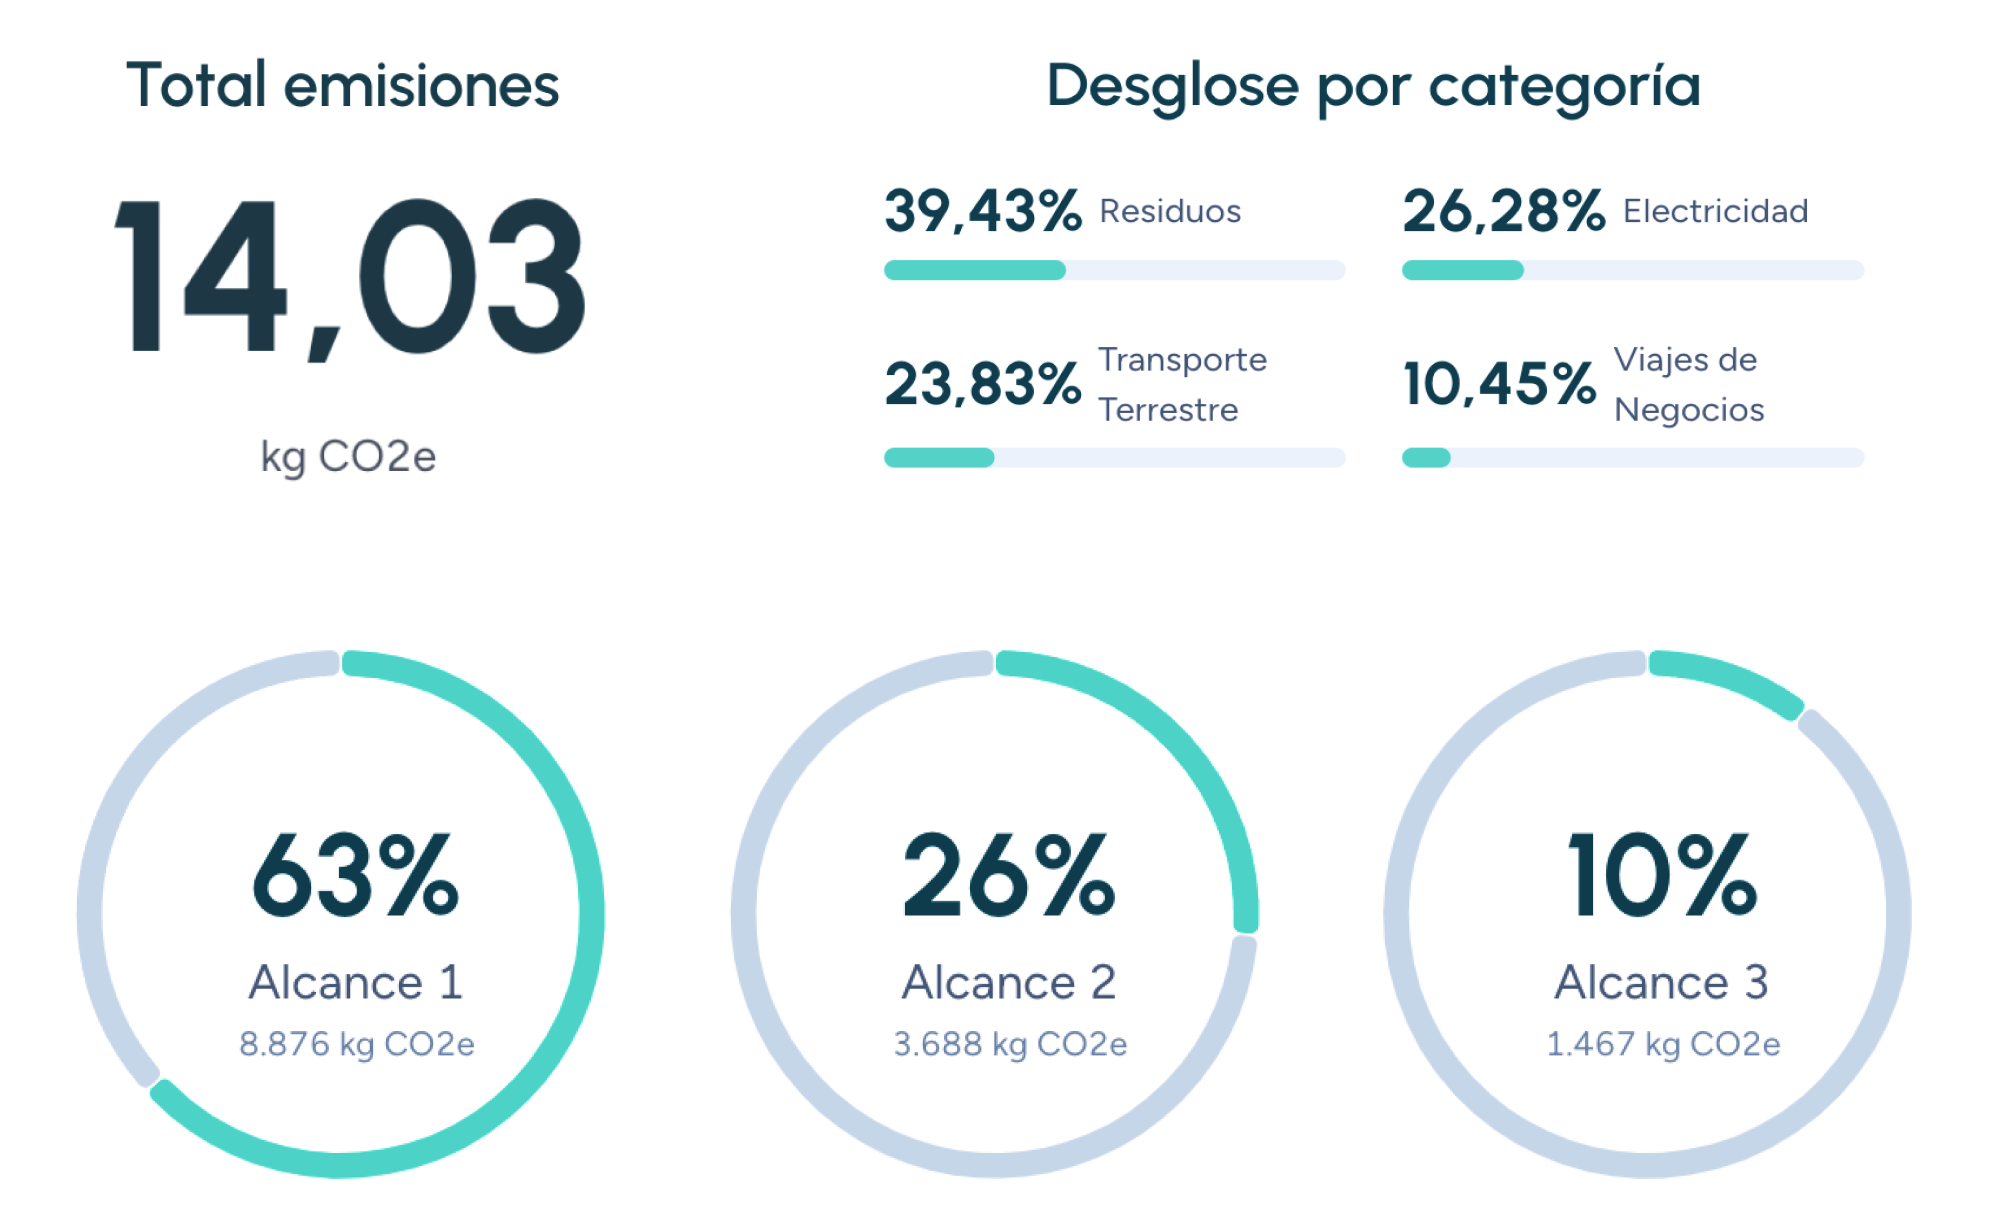
One of the most important sections, covering carbon footprint measurement across Scope 1, Scope 2 and Scope 3 following the GHG Protocol, natural resource use (water, energy) and waste management.
3. Social impact
Diversity and inclusion policies, labour conditions and employee well-being, and corporate social responsibility initiatives.
4. Economic impact
Financial performance, investment in sustainable projects, and the link between sustainability and profitability.
How to prepare a sustainability report
A structured approach keeps the process manageable:
1. Define objectives
Clarify the purpose: regulatory compliance, improving brand perception, or meeting stakeholder expectations.
2. Collect data
Data collection is one of the most demanding phases. Companies must gather reliable information on environmental, social and economic performance. Platforms like Manglai automate much of the analysis and offer tailored recommendations to streamline this step.
3. Analyse and structure
Turn the data into insight: identify trends, compare results year on year and define key performance indicators (KPIs).
4. Draft and design
Keep the report clear and accessible, avoiding excessive jargon, and use graphs and tables to aid readability.
5. Publish and communicate
Share the report with stakeholders to maximise its impact.
Standards and regulations for sustainability reporting
Several frameworks guide reporting:
1. Global Reporting Initiative (GRI)
One of the most widely used global standards, focused on impact reporting.
2. ESRS and IFRS Sustainability Disclosure Standards
The ESRS underpin CSRD reporting in the EU, while the ISSB standards (IFRS S1 and IFRS S2) provide an investor-focused global baseline. IFRS S2 absorbed the recommendations of the TCFD, which was disbanded in October 2023, so companies today report against IFRS S2 rather than the TCFD as a standalone framework.
3. GHG Protocol
The most recognised standard for carbon footprint measurement across Scope 1, 2 and 3 emissions.
Prepare your sustainability report with Manglai
A sustainability report lets companies measure and communicate their impact, meet tightening regulation and drive continuous improvement. Manglai helps companies measure their carbon footprint and prepare sustainability reporting aligned with global standards and the CSRD.
Companies that trust us
Related terms
See all termsEnvironmental Governance
What environmental governance is, why it matters for climate action, its key components, and how it connects to measuring and reducing the corporate carbon footprint.
Solid waste management in Peru (Legislative Decree 1278)
Legislative Decree 1278, Peru's Integrated Solid Waste Management Law, and its regulations set the duties of non-municipal waste generators: recovery as the first option, an internal register, a Minimisation and Management Plan inside the environmental management instrument, and annual and quarterly filings through SIGERSOL.
Sustainability disclosure in Colombia (Financial Superintendence)
Sustainability disclosure in Colombia is driven by Financial Superintendence circulars, chiefly External Circular 031 of 2021 for securities issuers and External Circular 015 of 2025 on environmental, social and climate risk. IFRS S1 and S2 are not mandatory: they sit in a voluntary convergence process led by the CTCP.
Guiding businesses towards net-zero emissions through AI-driven solutions.
Product & Pricing
What is Manglai
Features
SQAS
GLEC
GHG Protocol
ISO-14046
ISO-14064
Miteco certification
CSRD
CSDDD
Digital Product Passport
EINF
Prices
Customers
Partners
Solutions by role
Environmental consulting
ESG management solutions
Financial directors
General directors
HR managers
Operations directors
Quality and environment directors
Senior management
Solutions for investment funds
Supply chain managers
Sustainability managers
Transport responsible
© 2026 Manglai. All rights reserved