The Sustainability Accounting Standards Board (SASB) developed a widely used set of industry-specific sustainability disclosure standards. Since August 2022, technical responsibility for the SASB Standards has been transferred to the International Sustainability Standards Board (ISSB), part of the IFRS Foundation. The SASB name now refers to the standards themselves rather than to an active standard-setting board.
What are the SASB Standards?
SASB was founded in 2011 as an independent non-profit to develop sustainability accounting standards for companies. Its standards help businesses identify, measure and disclose the financially material environmental, social and governance (ESG) information that is most relevant to investors. They cover 77 industries, each with a tailored set of disclosure topics and metrics.
From SASB to the ISSB
- Consolidation: the Value Reporting Foundation (which housed SASB) was consolidated into the IFRS Foundation in 2022, and the ISSB now maintains and enhances the SASB Standards.
- Link with IFRS S2: the SASB Standards underpin the industry-based guidance that accompanies IFRS S2 on climate-related disclosures. Companies applying IFRS Sustainability Disclosure Standards are required to consider them.
- Legacy and ongoing review: the ISSB is reviewing and updating the SASB Standards so they remain relevant as global IFRS Sustainability Disclosure Standards develop.
SASB Standards and the carbon footprint
The carbon footprint, which measures a company's greenhouse gas (GHG) emissions, is a key sustainability indicator. The SASB Standards provide industry-specific guidance and, for many sectors, expect companies to disclose:
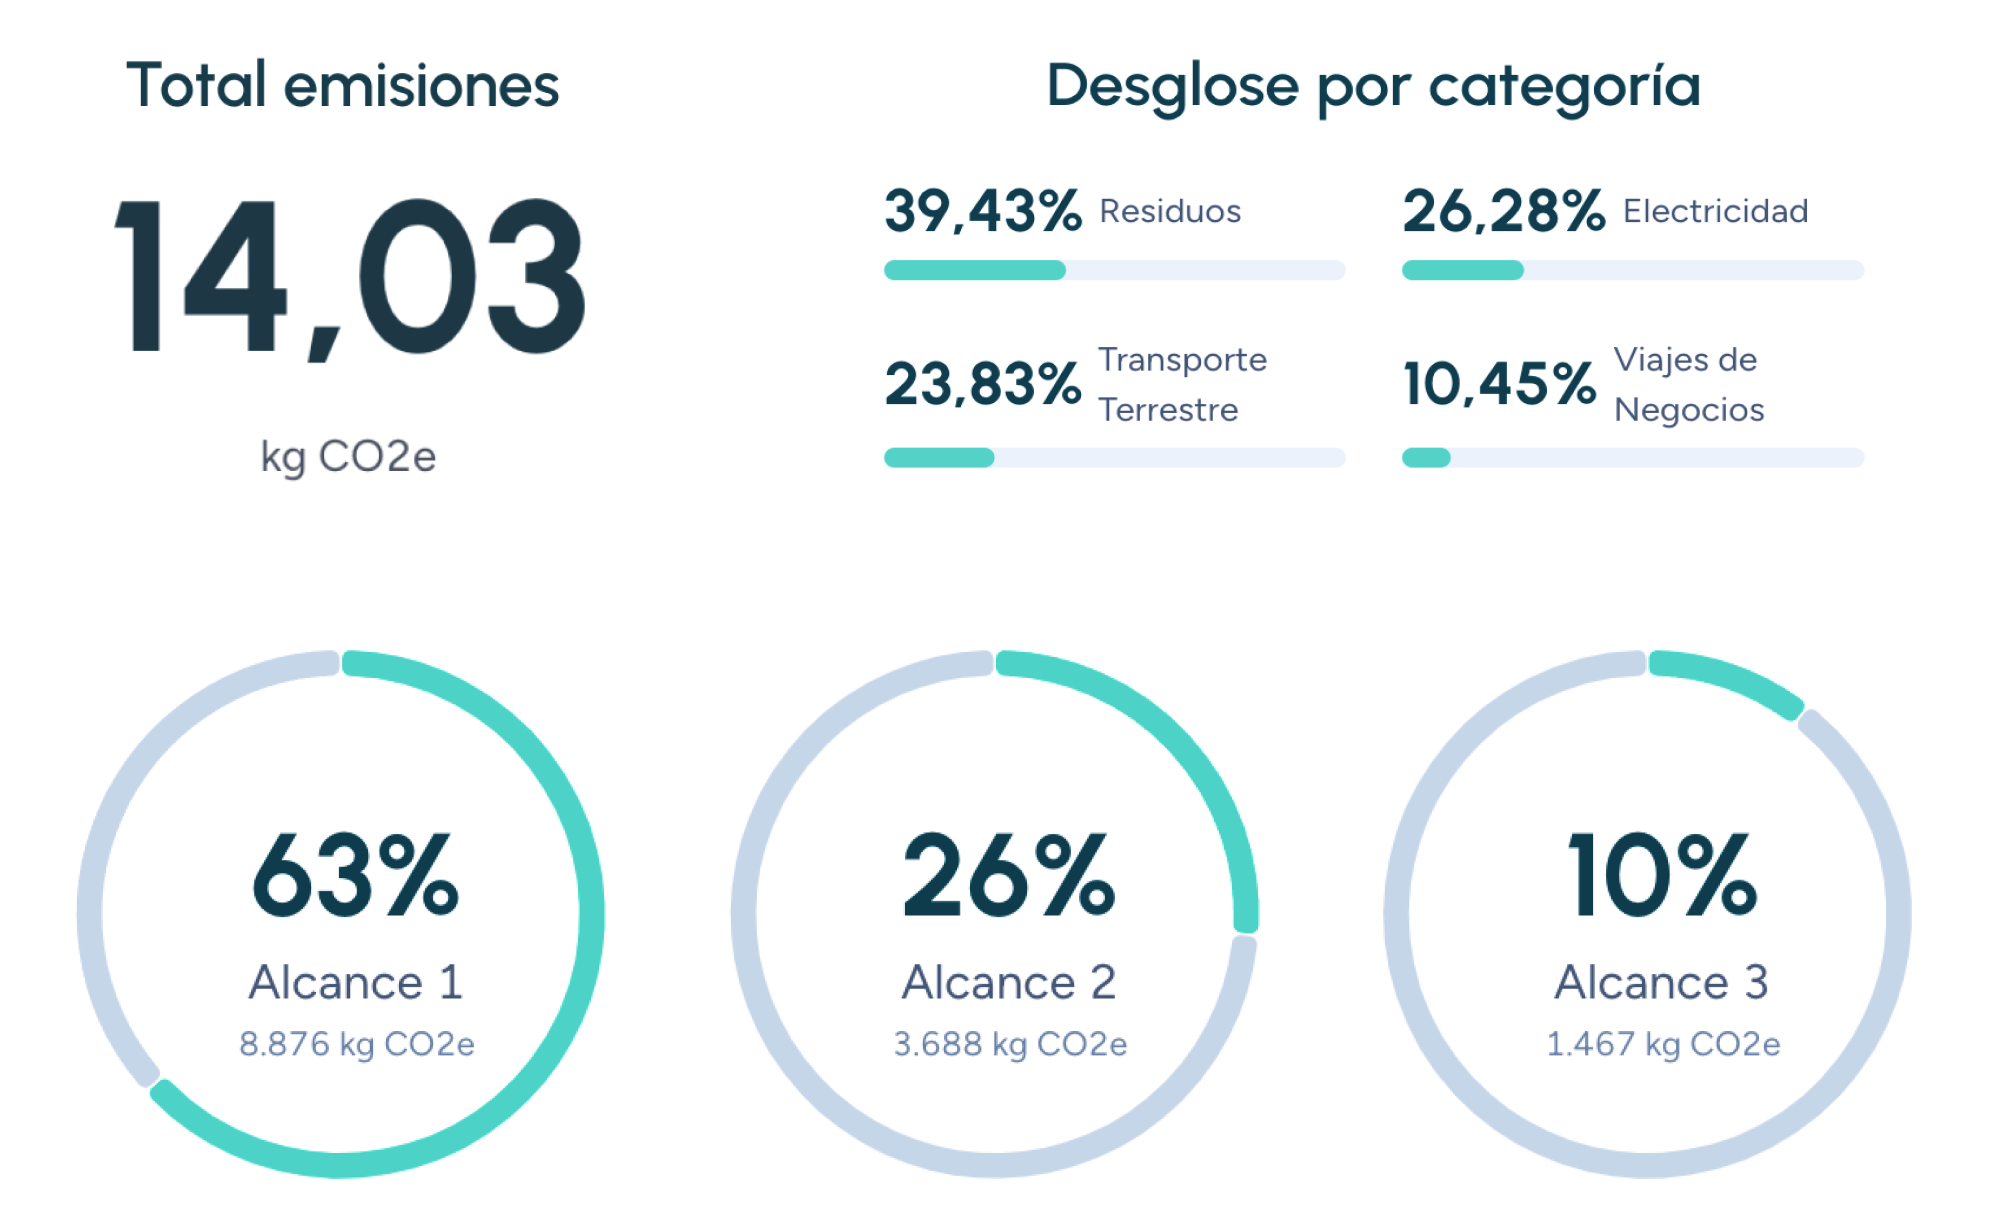
- Direct and indirect GHG emissions (Scope 1, Scope 2 and Scope 3).
- Emission reduction targets and progress towards them.
- Climate-related risks and opportunities.
- Strategies for managing carbon emissions.
Benefits of using the SASB Standards
- Transparency and accountability: standardised, comparable reporting for investors and stakeholders.
- Better-informed investment decisions: investors increasingly use ESG data, so clear disclosure can improve access to capital.
- Risk and opportunity management: the standards help identify and assess sustainability-related risks and opportunities.
- Operational efficiency: measuring ESG indicators reveals opportunities to reduce costs.
Relationship with other frameworks
- Global Reporting Initiative (GRI): a broader, impact-oriented reporting framework, while SASB focuses on financially material data for investors.
- TCFD: the Task Force on Climate-related Financial Disclosures, whose recommendations are now embedded in IFRS S2 (the TCFD was disbanded in 2023 and its monitoring role taken over by the IFRS Foundation).
By integrating the SASB Standards into their reporting, companies can strengthen ESG transparency, improve investor confidence and align with the consolidated global baseline being built by the ISSB. At Manglai we help companies measure their carbon footprint and prepare their sustainability reporting. Discover how Manglai can help you.
Manglai Newsletter
Regulatory updates and product news, once a month.
Companies that trust us
Related terms
See all termsSustainability Reporting Standards (NIS, Mexico)
The Sustainability Reporting Standards (NIS) are the framework issued by the CINIF in Mexico to standardise the reporting of environmental, social and governance (ESG) impacts.
Sustainability assurance
External, independent verification that lends credibility to sustainability information. The CSRD requires limited assurance, using standards such as the IAASB's ISAE 3000 and ISSA 5000.
Sustainability disclosure in Colombia (Financial Superintendence)
Sustainability disclosure in Colombia is driven by Financial Superintendence circulars, chiefly External Circular 031 of 2021 for securities issuers and External Circular 015 of 2025 on environmental, social and climate risk. IFRS S1 and S2 are not mandatory: they sit in a voluntary convergence process led by the CTCP.